by Stephanie Taub, Senior Counsel • 3 minutes
President Trump’s new Education Freedom Tax Credit will soon give more families the opportunity to provide a religious education to their children.
The Working Families Tax Cut Act, also known as the One Big Beautiful Bill, created Education Freedom Tax Credits that will soon be available. Beginning in January 2027, taxpayers who donate to qualifying scholarship-granting organizations may claim a dollar-for-dollar federal tax credit of up to $1,700. Married couples filing jointly may claim up to $3,400. Unlike an income-tax deduction, which merely reduces taxable income, this credit directly reduces federal tax liability.
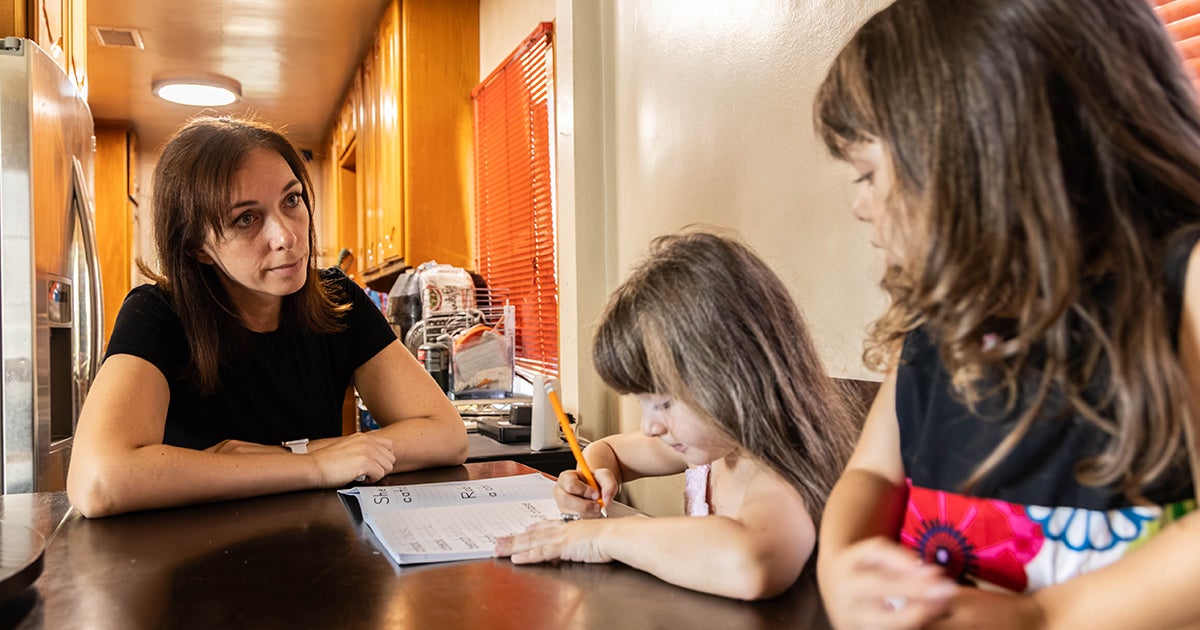
Those contributions turn into scholarships for K-12 students, covering eligible elementary and secondary education expenses, including private-school tuition, tutoring, and books. Under the program, eligible families can receive scholarships to send their children to religious schools as well. The program thus empowers parents to choose the education option that works best for their family rather than forcing every child into the same model.
The program also rests on a strong constitutional foundation built through years of school-choice litigation. In Trinity Lutheran Church of Columbia, Inc. v. Comer, the U.S. Supreme Court held that a church could not be barred from competing for a generally available public benefit solely because of its religious character. In Espinoza v. Montana Department of Revenue, the Court concluded that Montana could not exclude religious schools and the families choosing them from an educational-aid program merely because the schools were religious.
Then came First Liberty’s Carson v. Makin, a landmark victory in the broader religious-liberty and school-choice effort. Maine offered tuition assistance to families in certain areas but excluded schools providing religious instruction. The Supreme Court held that once Maine made tuition assistance available for parents to direct to public or private schools, it could not deny that benefit because a family selected a religious school.
These decisions did not require Congress to enact the Education Freedom Tax Credit. They did, however, establish the constitutional principle that government may not open an educational-benefit program to private choices and then treat religious choices as second-class. The Education Freedom Tax Credit puts that principle into practice by allowing scholarship support to follow families, including those choosing religious education.
Implementation is now approaching. On October 1, 2026, the Department of the Treasury and the Internal Revenue Service issued temporary and proposed regulations for the program. But there is a crucial condition: each state must opt in before students in that state can receive scholarships through participating organizations.
You can see if your state has opted in here: https://www.whitehouse.gov/schoolchoice/
Governors and state leaders therefore face a clear choice. They can open the door to privately funded educational opportunity, or they can deny their families access to a federal program available elsewhere. States should opt in—and affirm that educational freedom belongs to every family, including those who choose a religious education.